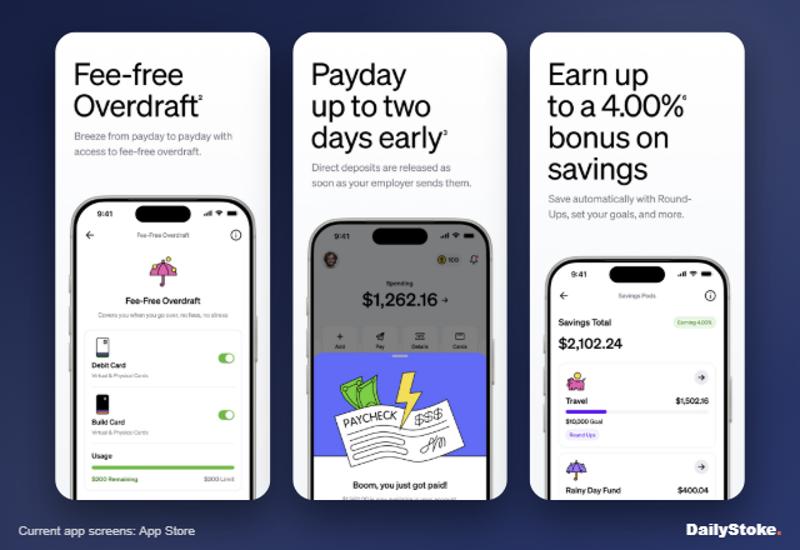
Current is a New York fintech built for people who live paycheck to paycheck. It gives you early pay, fee-free overdraft and up to three Savings Pods that earn a 4.00% bonus on their first $2,000 each, as long as your payroll goes in.
It is a good deal on small balances and a poorer one if you travel, use cash or save more than $6,000. Here is our Current review, built from Current’s own disclosures and deposit agreement, checked on October 29, 2026.
Our verdict
Current does the basics well for people on modest incomes: no monthly fee, paychecks up to two days early, a fee-free overdraft buffer and a savings bonus that beats most banks on the first $6,000. The rules are tight, though. Miss the $200 payroll deposit and the bonus drops to 0.25%; spend abroad and you pay 3%; use an out-of-network ATM and it costs $3.50. Pick Current for a small emergency fund and everyday spending, not as your only account.
Current at a glance
- Company: Current (App Store seller Finco Services, Inc.), New York
- Banking partners: Choice Financial Group and/or Cross River Bank, Members FDIC
- Monthly fee: $0; no minimum balance
- Savings: up to three Pods; 4.00% bonus on the first $2,000 in each with a $200+ payroll deposit in 35 days, otherwise 0.25%
- Overdraft: fee-free, amount varies, for direct deposit members
- ATMs: 40,000+ fee-free Allpoint ATMs; $3.50 out of network
- Optional subscription: Current Max, announced at $10 a month
- Ratings: App Store (US) 4.8 from 197K ratings; Google Play 4.4 from 179K reviews
Pros
- 4.00% bonus on up to $6,000 with a modest $200 payroll deposit
- No monthly or minimum balance fees
- Paychecks up to two days faster
- Fee-free overdraft and Paycheck Advance for direct depositors
- Free instant transfers between Current members
Cons
- Nothing earned above $2,000 per Pod
- 3% foreign transaction fee
- $3.50 out-of-network ATM fee and $3.50 to deposit cash at retailers
- Not a bank; FDIC pass-through cover depends on conditions
- $5 monthly inactivity fee after a year without activity
What Current does and who it is for
Current is an app-only checking account with a Visa debit card, Savings Pods, a secured charge card for building credit (the Build Card) and an optional crypto feature through Zero Hash. There are no branches; the company says it has no physical locations at all.
It is aimed at workers paid through payroll who want their money early and need a safety net at the end of the month. The account opens without a minimum deposit, and paychecks are released as soon as Current receives them, which can be up to two days before payday.
Is Current a real bank? FDIC protection explained
No. Current describes itself as “a financial technology company, not an FDIC-insured bank.” Banking services come from Choice Financial Group and/or Cross River Bank, Members FDIC, and your money can be covered up to $250,000 through FDIC pass-through insurance. Current’s own wording is that this applies “only if certain conditions are met,” and that otherwise funds may not be fully insured if a bank fails.
This is the standard fintech model, and both partners are established banks, but it is one step removed from holding an account at a bank directly.
Current Savings Pods: how the 4% bonus works
You can open up to three Savings Pods, each with its own goal. Current pays a bonus on the first $2,000 in each Pod, so up to $6,000 in total:
| Your status | Bonus rate | Applies to |
|---|---|---|
| At least one Eligible Payroll Deposit of $200+ within 35 days | 4.00% | First $2,000 in each Pod |
| No qualifying payroll deposit | 0.25% | First $2,000 in each Pod |
| Any status | 0.00% | Money above $2,000 per Pod |
The bonus is paid by Current, not by a bank, and posts daily once a Pod has earned at least a cent. Because it is a bonus rather than interest, it is reported on a 1099-MISC. The rate is variable. With all three Pods full at 4.00%, you would earn roughly $240 over a year.
Current Max is the paid upgrade, billed monthly. Current announced it at $10 a month when it launched in November 2025; its help pages today do not publish a price, and the app shows the fee before you subscribe. Max adds two percentage points to your existing Pods bonus (to 6% for payroll members, still on up to $6,000), 2 extra points per dollar on eligible Build Card spending, $20 more on your fee-free overdraft limit if you are eligible, and faster access to a live agent on the phone. At the launch price, the extra 2% on $6,000 is worth about $120 a year, roughly what the subscription costs, so Max only makes sense if you use the points and other benefits too.
Current fees
From Current’s deposit agreement with Cross River Bank, updated June 22, 2026, and its website:
- Monthly and minimum balance fees: none
- Out-of-network ATM or over-the-counter withdrawal: $3.50 under the Cross River account agreement, plus the ATM owner’s fee (Current’s Spend page quotes $2.50); Allpoint ATMs in the network are free
- Cash deposits: $3.50 per deposit at participating retailers
- Foreign transactions: 3% of the amount, minimum $0.50
- Card replacement: $5, or $30 expedited
- Inactivity: $5 a month after 12 consecutive months without activity
- Current Pay transfers between members: free, up to $2,500 per 24 hours
Overdraft, Paycheck Advance and the Build Card
Fee-free overdraft is available on individual accounts once you have $200 or more of eligible direct deposits in the past 35 days. Current sets the limit, which it can change at any time, and you have 60 days to bring the balance back above zero. There are no fees or interest.
Paycheck Advance, offered by Finco Advance LLC, gives you early access to part of your next paycheck. Current describes it as earned wage access, not a loan, and it involves no credit check. Advances run from $25 to $1,000, with the top amounts for customers who get $200 or more of eligible payroll deposits; the amount you are offered appears in the app and can change. Standard delivery is free and takes up to three business days. Getting the money within about an hour costs an optional Instant Access Fee, which Current shows in the app rather than publishing, and which you repay with the advance. There is no interest or tipping, and repayment comes out of your next eligible payroll deposit.
The Build Card is a secured charge card issued by Cross River Bank. You spend money you have moved onto it and Current reports your payments, with the aim of building a credit history. Eligible purchases with a $200 payroll deposit or Max earn points redeemable for cash back.
What we liked
The $200 payroll test for the 4.00% bonus is far easier to meet than Chime’s $3,000 threshold for 4.00% or SoFi’s $5,000 deposit alternative, which makes Current one of the best-paying homes for a small emergency fund.
Early pay and fee-free overdraft are well suited to its audience, and the app is highly rated: 4.8 from 197,000 ratings on the US App Store.
What we did not like
The fees bite in exactly the places Chime and Capital One 360 have dropped them. A 3% foreign transaction fee rules Current out as a travel card, and $3.50 for out-of-network cash withdrawals or cash deposits adds up for anyone who handles cash. The $2,000 cap per Pod also means the bonus stops helping once your savings grow.
How Current compares
Current vs Chime: Chime charges no foreign transaction fee, has 47,000+ fee-free ATMs, a lower $2.50 out-of-network fee and SpotMe up to $200, but pays 4.00% only to members with $3,000 a month of direct deposits. Read our Chime review.
Current vs SoFi: SoFi is a chartered bank paying 3.30% APY on all savings with direct deposit and offers up to $3 million of FDIC cover. Above $6,000 of savings, SoFi wins easily. See our SoFi Checking and Savings review.
Current vs Varo: Varo pays 3.75% APY on the first $5,000 with $800 of monthly direct deposits and is a bank in its own right; Current’s bonus is higher and its deposit test lower.
Who should open a Current account
Current suits payroll workers with savings under $6,000 who want early pay and an overdraft buffer without fees. It is a weaker choice for travelers, cash users and anyone with larger savings, who should pair it with or choose a high-yield account elsewhere.
Current FAQs
Is Current FDIC insured?
Current is not a bank. Its accounts are provided by Choice Financial Group and/or Cross River Bank, Members FDIC, and your money can be covered up to $250,000 through pass-through insurance if certain conditions are met.
How much do Current Savings Pods pay?
A 4.00% bonus on the first $2,000 in each of up to three Pods if you have an Eligible Payroll Deposit of $200 or more within 35 days, or 0.25% if not. Money above $2,000 per Pod earns nothing. The rate is variable.
Does Current charge foreign transaction fees?
Yes. Current’s deposit agreement lists a 3% fee on the full transaction amount, with a minimum of $0.50.
What is Current Max?
An optional monthly subscription that adds two percentage points to the Savings Pods bonus, extra rewards points on eligible spending and priority support. It was announced at $10 a month in November 2025.