Chime is the app that persuaded millions of Americans that a checking account does not have to cost anything. It charges no monthly fee, no overdraft fee and no foreign transaction fee, and its SpotMe feature quietly covers small overdrafts instead of punishing them.
These days, though, what you get from Chime depends heavily on how much of your pay goes into it. Savings rates, cashback and the useful extras now sit behind free membership tiers set by your direct deposits. Here is our Chime review: what it costs, who holds your money, and when a rival makes more sense.
Our verdict
Chime is one of the best accounts in the US for avoiding fees on everyday spending, and SpotMe is a genuinely kind piece of design for anyone who lives close to zero at the end of the month. The savings rate is competitive only once you reach Chime Plus or Prime, and Chime is not a bank, so you rely on partner banks for FDIC cover. If your paycheck is going in anyway, it is an easy recommendation; if you want a high savings rate on a larger balance, SoFi or Ally does more.
Chime at a glance
- Owner: Chime Financial, Inc., San Francisco (Nasdaq: CHYM, listed June 2025)
- Banking partners: The Bancorp Bank, N.A. or Stride Bank, N.A., Members FDIC
- Monthly fee: $0, with no minimum balance
- Savings APY: 1.00% standard, 3.00% Chime Plus, 4.00% Chime Prime (variable, effective October 6, 2026)
- Overdraft: SpotMe, $20 to $200, no fee
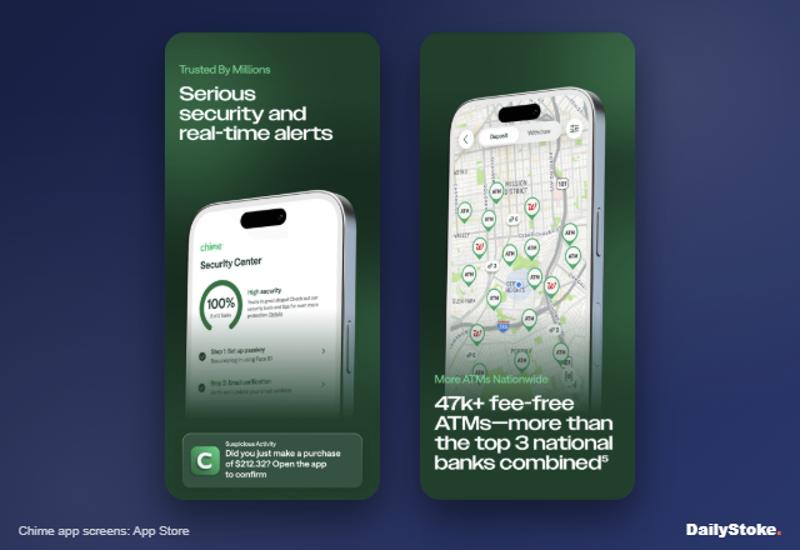
- ATMs: 47,000+ fee-free; $2.50 out of network plus the owner’s fee
- Ratings: App Store (US) 4.8 from 1.6M ratings; Google Play 4.7 from 1.1M reviews
Pros
- No monthly, overdraft or foreign transaction fees
- SpotMe covers overdrafts up to $200 without a fee
- Paychecks up to two days early
- Free secured Credit Builder card with no annual fee or interest
- Excellent app ratings on both stores
Cons
- Not a bank: protection runs through partner and program banks
- Best savings rate needs $3,000 a month of direct deposits
- $2.50 out-of-network ATM fee, plus whatever the ATM owner charges
- Instant MyPay advances and outbound instant transfers cost extra
- Some Chime marketing pages quote rates that do not match the dated disclosures
What Chime does and who it is for
Chime offers checking with a Visa debit card, savings, a secured credit card and investing through Atomic Invest, all in the app.
It is built for people paid through payroll who want a simple account without fee traps. Chime’s account opening has no minimum deposit, and once your direct deposit arrives it is usually available up to two days before your scheduled payday, because Chime releases funds when it receives the payment file.
Is Chime a real bank? How your money is protected
Chime describes itself as “a financial technology company, not a bank.” Your checking money is held at The Bancorp Bank, N.A. or Stride Bank, N.A., both Members FDIC. Savings go a step further: Chime sweeps them to a network of program banks (24 linked to Bancorp and 26 to Stride on lists dated June 10, 2026), each of which offers FDIC cover of $250,000 per depositor, per ownership category.
Chime’s disclosures add two caveats: money placed with the “excess bank” beyond the insured limits is not FDIC-insured, and you must track any other money you hold at the same program banks.
Chime fees and limits
Chime’s fee schedule is short:
- Monthly, minimum balance and overdraft fees: none
- Out-of-network ATM or over-the-counter withdrawal: $2.50 per transaction, plus any third-party fee
- Cash deposits: free at Walgreens and Duane Reade; other retailers may add their own fee
- Foreign transaction fee: none, according to Chime’s help center
- Outbound instant transfer: 1.75% of the amount; standard transfers are free
- MyPay instant advance: 3% of the advance, minimum $2 and maximum $5; free if you wait up to 24 hours
- Instant Loans: finance charge at an APR of up to 36%
Chime membership tiers and savings APY
Chime now sorts members into three free tiers based on the direct deposits it sees over 34 days. You cannot choose a tier; it changes automatically.
| Tier | How to qualify | Savings APY | Card cashback | Extras |
|---|---|---|---|---|
| Chime | Open an account | 1.00% | Chime Deals offers | Early pay |
| Chime Plus | One $200+ direct deposit, or $400+ in total | 3.00% | 2% on one monthly category (up to $1,500 of spending) | Priority 24/7 support, 0.10% managed investing fee |
| Chime Prime | $3,000+ of direct deposits | 4.00% | 5% on one monthly category (up to $1,500) | Priority Pass lounges, Visa Signature Concierge, travel data, two international ATM fee refunds a month, no managed investing fee |
The APYs are variable and come from Chime’s disclosure effective October 6, 2026. There is no minimum balance; you need $0.01 in savings to earn interest. Some older Chime pages still quote 0.75% or 3.75%, so go by the dated disclosure.
SpotMe, MyPay and Credit Builder
SpotMe is Chime’s answer to overdraft fees. Once you have a qualifying direct deposit of $200 or more in the past 34 days and an activated card, Chime will cover debit card purchases and cash withdrawals that take you below zero, starting at $20 and rising to as much as $200 based on your history. Anything beyond your limit is declined rather than charged, and the negative balance is repaid from your next deposit.
MyPay lets you draw part of your earned pay before payday. Chime’s headline says up to $500, while its footnotes describe credit limits of $20 to $1,000 per pay period depending on eligibility. It is free if you wait up to 24 hours; instant funding costs 3%, between $2 and $5.
Credit Builder is a secured Visa credit card with no annual fee and no interest. You move money in, spend against it, and Chime reports your payments to the credit bureaus.
What we liked
The fee schedule is refreshingly short: no monthly charge, no overdraft penalty and no foreign transaction fee, which is rarer than it should be among fee-free accounts.
SpotMe is the stand-out. A $200 buffer will not save a bad month, but it stops the cycle of a $5 coffee triggering a $35 penalty, and declining anything over the limit is the right call.
The app itself is very highly rated: 4.8 from 1.6 million ratings on the US App Store and 4.7 from about 1.1 million reviews on Google Play.
What we did not like
The tier system makes Chime less generous to people with smaller or irregular incomes. Without a direct deposit you earn 1.00% on savings; getting to 4.00% means $3,000 or more of deposits every 34 days, which is a big ask for many of the people Chime is aimed at.
The partner-bank model adds a layer between you and your money. It is common, and Chime’s partners are established banks, but if something goes wrong it is slower to untangle than a direct bank account.
Cash users should also check their local options. The $2.50 out-of-network fee plus the ATM owner’s own fee can easily reach $5 a withdrawal.
How Chime compares
Chime vs SoFi: SoFi is a chartered bank and pays 3.30% APY on savings with any eligible direct deposit, plus up to $3 million of FDIC cover through its deposit program. Chime beats it on overdraft cover ($200 against $50) and app ratings on Android. See our SoFi Checking and Savings review.
Chime vs Current: Current pays a 4.00% bonus on up to $6,000 with just a $200 payroll deposit, which beats Chime for small savers, but it charges 3% on foreign transactions. Read our Current review.
Chime vs Varo: Varo is a bank in its own right and pays 3.75% APY on the first $5,000 with $800 of monthly direct deposits. Chime has more fee-free ATMs and no foreign transaction fee.
Who should open a Chime account
Chime is a good fit if your paycheck arrives by direct deposit, you have been hit by overdraft fees before, and you want an app that is simple and well built. It is especially strong if your monthly deposits reach $3,000, when the Prime savings rate and travel perks kick in.
Look elsewhere if you keep large balances or deposit a lot of cash.
Chime FAQs
Is Chime FDIC insured?
Chime itself is not. Your money is held at The Bancorp Bank, N.A. or Stride Bank, N.A., Members FDIC, and savings are spread across program banks. FDIC cover is $250,000 per depositor, per insured bank, per ownership category, and money held with the excess bank is not insured.
What is Chime’s savings interest rate?
It depends on your tier: 1.00% APY as standard, 3.00% for Chime Plus and 4.00% for Chime Prime, effective October 6, 2026. Rates are variable and there is no minimum balance.
How much can SpotMe cover?
Limits start at $20 and can rise to $200, based on your direct deposits, card spending and account history. Boosts from other members can add $5 at a time. You need a qualifying direct deposit of $200 or more in the past 34 days.
Does Chime charge foreign transaction fees?
No. Chime’s help center says it does not charge foreign transaction fees. ATM owners abroad may still charge their own fees, and Chime’s $2.50 out-of-network fee can apply.
Who owns Chime?
Chime Financial, Inc., based in San Francisco. It listed on Nasdaq under the ticker CHYM after pricing its IPO in June 2025.